Home Loan Finance Online Business Loan Repayment Calculator
Explore potential business finance scenarios with our Business Loan Calculator. Test different borrowing amounts, interest rate assumptions and loan structures to see how various scenarios may influence your estimated repayments and overall finance costs.
All results provided by these home loan calculators are estimates only, based on the information you enter and the assumptions used. They are general information, not a quote, offer of finance, approval, assessment of your personal eligibility or personalised recommendation. Actual repayments and costs may differ. See our general information disclaimer for more details.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Loan Amortisation Calculator
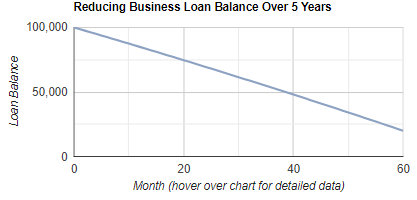
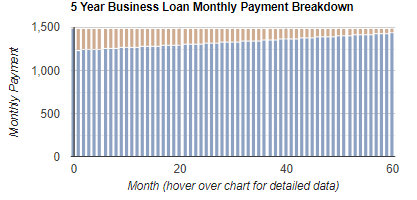
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
When embarking on the journey of homeownership, many Australians find themselves navigating the complex world of home loans. On the surface, the mortgage process might seem straightforward. You find a home, secure a loan, and make payments until it’s fully paid off. However, the reality is more intricate, involving various fees and charges that can quickly add up. - read more
For many Australian consumers, buying a property is one of the most significant financial decisions they'll make. Navigating the home loan landscape effectively is crucial to easing the journey toward property ownership. - read more
Refinancing a home loan is a process many Australian homeowners consider at some point. But what exactly does it mean? In simple terms, refinancing involves replacing your existing mortgage with a new one—usually with different terms. Homeowners often look into refinancing for several reasons, whether it’s to secure a lower interest rate, consolidate debts, or switch from a fixed to a variable rate (or vice versa). - read more
Low deposit home loans can help eligible Australian borrowers buy with less than a 20% deposit, but lenders mortgage insurance may apply and can add to the cost of borrowing. - read more
Fresh Domain analysis has put a useful reality check around Australia’s housing downturn: cheaper advertised prices do not automatically make a first home easier to afford. The 5 November 2026 analysis found combined capital city house prices had fallen by about $81,000, or 6.2 per cent, from their peak, yet estimated monthly mortgage repayments were only about $10 lower. - read more
Australian first-home buyers have a fresh repayment hurdle to factor into their planning, with major banks moving to lift variable mortgage rates after the Reserve Bank of Australia raised the cash rate target to 4.85 per cent in early November. The change does not mean every buyer will face the same outcome, but it does make one point clear: a lower property price is only useful if the loan remains affordable under current and tested repayment settings. - read more
The 64th Melbourne Boat Show has given Australia’s boating market another useful demand signal, with organisers reporting more than 42,000 visitors at Docklands from 15 to 18 October 2026. The result was stronger than last year’s reported 39,000 attendance and came after four days of favourable weather, free entry and a waterfront layout spanning more than a kilometre of marina and land-based displays. - read more
A new Australian freight alliance, FLEETLEAP, has been launched to help truck operators make more informed decisions about fuel efficiency, emissions reduction and electric truck investment. Announced at the NatRoad National Conference on the Gold Coast on 6 November 2026, the project brings together transport associations, energy specialists, insurers and technology providers at a time when operating costs and technology choices are putting extra pressure on fleet planning. - read more